BLOG
Accounts Receivable Financing: How It Works and Why Operations Teams Love It
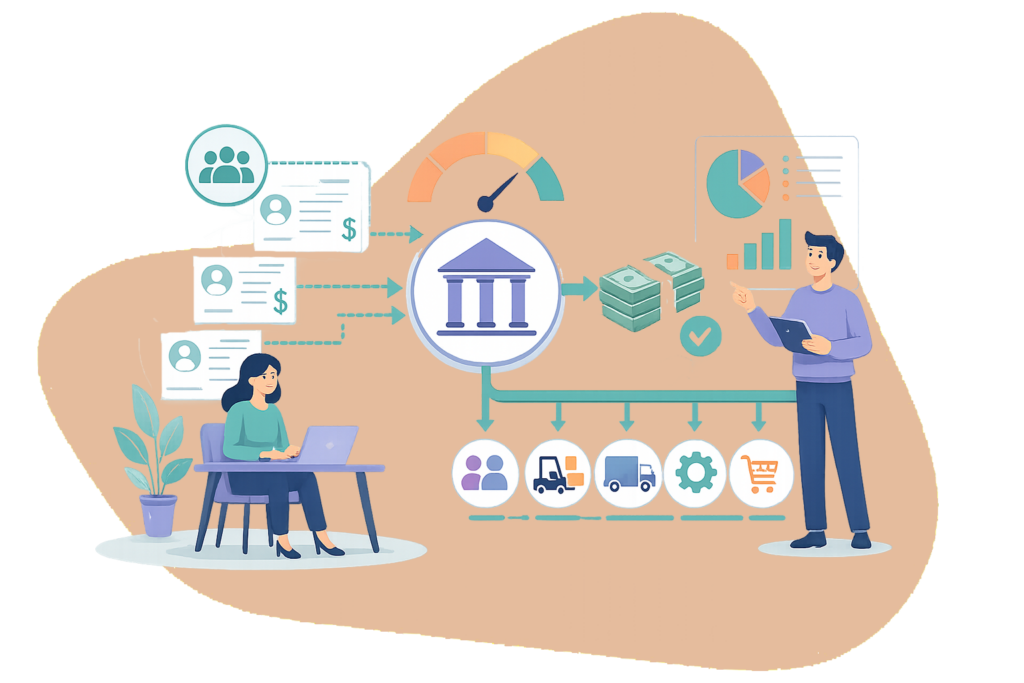
Your customers owe you money, but your bills are due now. That gap creates real operational strain for mid-market businesses. It affects payroll, inventory, and vendor relationships.
Accounts receivable, or AR, financing bridges that gap. It lets you borrow against unpaid invoices rather than waiting 30, 60, or 90 days for customers to pay. We will walk through how accounts receivable financing works. We will also cover the specific benefits operations teams value most, and what features matter when choosing a commercial lending marketplace to find the right lender like Cerebro Capital.
For a deeper product overview, see our explainer on accounts receivable financing.
What is accounts receivable financing
AR financing allows businesses to borrow against unpaid customer invoices to obtain working capital. This solution unlocks funds tied up in invoice cycles, which supports operations and growth without waiting for customer payments.
Important terms explained:
- Accounts receivable: The amounts that customers owe a business for goods or services already delivered.
- Advance rate: The percentage of the invoice value that the lender advances to you upfront. The rest is held in reserve and released when the customer pays the invoice.
- Borrowing base: The total amount of eligible receivables times the advance rate minus reserves and dilution. That calculation sets how much you can draw.
Common structures you will encounter:
- AR revolving line of credit or ABL facility: A loan secured by receivables using a borrowing base formula. Receivables stay on your balance sheet. See how AR fits within asset-based lending.
- Invoice factoring: You sell invoices to a factor. Typical advances run 70 to 90 percent, and with strong debtors can reach the high 80s or 90s per invoice. Factor fees often run 1.5 to 2.5 percent per invoice cycle.
- Selective or spot factoring: You choose invoices to sell case by case for flexibility.
Accounts receivable financing can be a strategic tool for improving cash flow while keeping control of your receivables. T**he accounts receivable financing market grew from 2025 to 2026 at a compound annual growth rate (CAGR) of 11.3%.**
Key differences from factoring:
Unlike factoring, where invoices are sold to a third party, AR financing uses invoices as collateral. You retain ownership of receivables and borrow against them rather than selling them.
How accounts receivable financing works
Mechanics of accounts receivable financing:
- Invoice submission: You submit eligible invoices to the lender for consideration.
- Verification and evaluation: The lender verifies invoices and evaluates your customers’ payment histories.
- Advancement of funds: Upon approval, the lender advances a percentage of the invoice value. Funding is often within one to two days.
- Customer payment: Your customer pays under normal terms, often without any change to your process if the facility is non-notification.
- Release of remaining balance: When the customer pays, the lender releases the reserve balance to you, minus fees.
This process creates a revolving source of working capital that expands and contracts with your invoicing. AR financing is especially useful because a significant percentage of B2B invoices arrive late. According to Kaplan Collection Agency, 55 percent of U.S. B2B invoiced sales are overdue. Atradius’ 2024 U.S. Payment Practices Barometer similarly finds roughly half of B2B invoices are paid late, increasing working-capital pressure on suppliers (Atradius — Payment Practices Barometer: B2B Payment Practices Trends, United States 2024).
Want to see this in practice? Review our receivables financing case study.
Advance rate and borrowing base: how they drive capacity
Two mechanics determine cash availability:
- Borrowing base formula: Eligible receivables × advance rate − reserves − dilution.
- Advance rate: Often 70 to 90 percent for AR collateral depending on your debtor quality, aging, and concentration.
What reduces eligibility:
- Aging: Invoices past 90 days are commonly excluded. Some programs exclude an entire customer if too many of that customer’s invoices are past due.
- Concentration: Many lenders cap a single customer at about 20 to 25 percent of eligible AR. Amounts above the cap are often ineligible or reserved.
- Dilution and disputes: Credits, returns, allowances, and write-offs lower effective availability. Disputed invoices are usually excluded.
Quick illustration:
Assume $1,000,000 in AR. After aging and dispute exclusions, eligible AR is $800,000. Advance rate is 85 percent. That yields $680,000. Reserves of $30,000 and expected dilution of $20,000 reduce availability to $630,000. That is the most you can typically draw.
Regulatory guidance for ABL programs notes receivables past normal trade terms are commonly excluded from the borrowing base, and cautions that concentration and historic dilution materially reduce effective advance rates (Comptroller’s Handbook — Asset-Based Lending, Office of the Comptroller of the Currency).
Key benefits of accounts receivable financing for operational needs
AR financing is favored by operations teams because it addresses the timing mismatch between delivering value and receiving cash.
- Faster cash conversion and predictability: You forecast liquidity from invoiced sales instead of uncertain collection timing. This supports payroll, vendor payments, and inventory planning.
- Stable funding for payroll, vendors, and inventory:
- Payroll and benefits
- Supplier and vendor payments
- Raw materials and inventory
- Equipment maintenance
- Seasonal staffing
- Flexible capacity that scales with sales: As receivables grow, availability grows automatically without renegotiating limits.
- Fewer covenants than term debt and no equity dilution: You preserve ownership and maintain flexibility for strategic decisions.
- Real-time visibility: Many facilities include dashboards that show availability, advances, and projected cash, which helps operations teams plan daily.
Deloitte’s working capital research shows leading companies improve liquidity by shortening cash conversion cycles and that receivables pressure (rising DSO) remains a key driver of short-term working-capital needs.
Accounts receivable financing compared to other working capital options
Understanding where AR financing fits among your choices helps you select the right tool.
| Feature | AR Financing | Factoring | Line of Credit | Cash Flow Term Loan |
|---|---|---|---|---|
| Collateral | Invoices are used as collateral. | Invoices are sold to the factor. | Varies; may include AR, inventory, or other assets. | Cash flow and EBITDA are key. May require guarantees or security. |
| Customer notification | Often no notification. | Customers are usually notified and pay the factor. | Typically no notification. | No notification. |
| Funding speed | Fast once set up. | Fast per sale of invoices. | Moderate during setup. | Slower due to underwriting. |
| Scalability | Grows with sales via borrowing base. | Grows with sales via volume. | Often a fixed limit unless amended. | Fixed amount tied to cash flow. |
AR financing vs factoring
AR financing: You keep ownership and collections. You pledge invoices and draw against a borrowing base.
Factoring: You sell invoices. The factor typically collects directly, which can affect customer relationships. Non-recourse options exist but usually price higher and often exclude disputes and offsets.
AR financing vs business line of credit
Lines of credit: Fixed limits that require amendments to increase. May include broader collateral and financial covenants.
AR financing: Availability flexes with receivables, which can better match working capital cycles.
AR financing vs cash flow term loans
Cash flow term loans: Fixed proceeds and set amortization for defined projects or acquisitions.
AR financing: Revolving working capital tool that flexes with monthly needs.
Considering a blended approach for growth initiatives beyond AR financing? Explore growth capital loans.
For tailored guidance, consider contacting us or visiting our commercial lending marketplace overview.
Who qualifies for accounts receivable financing
Lenders focus on the credit quality of your customers and the performance of your receivables.
Typical criteria:
- B2B invoicing: Commercial customers with established pay histories.
- Clean AR operations: Accurate invoicing, consistent terms, and organized aging reports.
- Payment performance: Reasonable DSO and low dispute rates.
- Concentration profile: No outsized reliance on a single customer, or evidence of concentration management.
- Documentation readiness: Current AR aging, financial statements, and customer lists.
Mid-market companies often find AR facilities more accessible than unsecured credit because receivables collateral supports the advance.
Explore common structures and eligibility on our AR financing options page.
Features to consider when choosing a commercial lending marketplace
Mid-market businesses benefit from marketplaces that aggregate multiple lender options. Not all marketplaces deliver equal value.
Breadth and quality of lender network
A larger network improves odds of a fit by industry, size, and structure. Cerebro Capital connects businesses to best-fit lenders from our network of 2,200+ institutions that specialize in mid-market transactions.
Mid-market expertise
Mid-market underwriting must account for complex financials, customer concentration, and growth trajectories. Cerebro Capital focuses on these needs rather than generic small business templates.
Data-driven matching and term sheet comparison
Technology that targets lenders most likely to fund your profile saves time. Cerebro Capital provides curated matches and side-by-side term sheet comparisons so you avoid juggling spreadsheets.
Transparent pricing and automated workflow
Know the total cost and eliminate manual friction. Cerebro Capital streamlines document collection, lender communication, and status tracking so you move from application to close efficiently.
Dedicated capital markets guidance
Expert support during underwriting and closing is essential. Our team acts as a fractional capital markets desk to shape requests, manage lender dialogues, and navigate diligence.
For examples of how this comes together, see our AR ABL case study.
How to secure accounts receivable financing
Step 1. Assess your AR aging and working capital gap
Analyze your aging to size the facility to your cycle length and cash need. Identify late buckets and any recurring disputes that could reduce eligibility.
Step 2. Gather financials and concentration data
Prepare your AR aging, financial statements, customer list with concentration percentages, and collection history. Clean, consistent invoices and clear remittance data speed funding.
Step 3. Engage a commercial lending marketplace
Use Cerebro Capital to reach multiple lenders at once. Our process increases competitive tension and surfaces structures that fit your industry and collateral profile.
Step 4. Compare term sheets and negotiate
Compare advance rates, fees, reserves, covenants, monthly minimums, unused-line fees, and termination terms. Confirm how non-recourse is defined, assignment notices, and UCC filings. Cerebro Capital supports objective comparisons and negotiation strategy.
Step 5. Close, fund, and monitor performance
Track borrowing base utilization, dilution, and customer aging weekly. Use dashboards to forecast availability and alert on concentration breaches. Adjust line size and reserves as your sales cycle evolves.
Common risks and how to avoid them
- Customer concentration: Many lenders cap a single customer at about 20 to 25 percent of eligible AR. Breaches reduce availability. Mitigate by diversifying customers, setting internal limits, or considering non-recourse features or insurance for large buyers.
- Dilution and disputes: High credit notes, returns, or write-offs reduce eligibility. Tighten billing accuracy and dispute resolution. Maintain clear POs, proof of delivery, and acceptance documentation.
- Hidden fees and volume minimums: Translate fees to annualized cost. Watch for monthly minimums, unused-line fees, and tiered aging add-ons. Cerebro Capital emphasizes transparent comparisons to avoid surprises.
- Over-reliance on short-term financing: AR financing bridges timing gaps but does not fix profitability. Pair with operational improvements and, if needed, longer-horizon capital solutions.
- Customer relationship concerns: If confidentiality matters, confirm non-notification and lockbox terms, plus how payments are handled and whether assignment notices are sent.
To explore related structures and collateral combinations, review asset-based lending options.
FAQs about accounts receivable financing
Will my customers know I am using accounts receivable financing?
Often no. Many AR facilities are non-notification, so you retain collections. With factoring, the factor typically notifies customers and collects directly. Cerebro Capital helps you align structure with customer relationship goals.
Is accounts receivable financing considered debt on my balance sheet?
Yes. An AR revolving line of credit is a loan secured by receivables. It appears as a liability and does not dilute equity. Your accountant will confirm presentation under applicable accounting rules.
Can seasonal or high-growth businesses use AR financing?
Yes. Availability scales with receivables, which is valuable for seasonal spikes or rapid growth. Cerebro Capital can model advance availability across high-demand periods.
What happens if a customer does not pay an invoice that was financed?
In most recourse facilities, you must repay the advance. Non-recourse options typically price higher and usually only cover customer insolvency, not disputes or offsets. Cerebro Capital clarifies these definitions when comparing offers.
Can I use accounts receivable financing alongside other credit facilities?
Yes. Lenders coordinate via intercreditor agreements to define collateral priorities. Cerebro Capital manages this process across your lender group.
How do advance rate and borrowing base affect cash flow capacity?
Availability equals eligible AR times the advance rate minus reserves and dilution. Small changes in advance rate or concentration caps can materially change daily liquidity. Cerebro Capital’s tools help you see this impact before you sign.
What features should I look for in a commercial lending marketplace to secure AR financing?
Focus on lender network breadth, mid-market expertise, transparent pricing, technology for matching and comparisons, and hands-on support. Cerebro Capital’s lender network and workflow deliver these advantages.
What qualification criteria do lenders prioritize for AR financing?
Clean aging, consistent terms, strong debtor credit, manageable concentration, and well-run AR operations. Be ready with aging reports, financials, and evidence of collection performance. Cerebro Capital streamlines packaging and presentation to lenders.
How can operations teams forecast cash flow using AR dashboards and metrics?
Monitor DSO, aging buckets, concentration, dilution, and borrowing base availability. Pair daily sales with expected advance rates and reserve changes to project draws. Cerebro Capital can provide views that align AR metrics with facility availability.
How can businesses mitigate customer concentration and default risk when using AR financing?
Add customers to reduce concentration, set internal caps, tighten buyer credit vetting, and consider non-recourse structures or credit insurance for large accounts. Cerebro Capital helps negotiate structures that balance price and protection.
Author: Cerebro Capital Capital Markets Team
Published: May 8, 2026
Updated: October 7 , 2026
About the author
The Cerebro Capital Capital Markets Team advises mid-market companies on debt strategy, lender selection, and execution. We leverage a 2,200+ lender network and data-driven matching to source competitive AR financing, ABL facilities, and growth capital aligned to cash flow and collateral
Related Content
The world of middle-market lending has changed. Before COVID-19, traditional lenders showed flexibility as they worked to expand their books of business.
Increase the Chances of Closing a Loan
Significant disruptions to the lending landscape in the past four months have left corporate borrowers scrambling to stay on top of changing requirements
CFOs need to be constantly aware of how their company’s financial performance and market shifts affect its debt capacity, which is the best measure of your business’ ability to borrow.
Ready to get started?
Join the thousands of mid-sized companies who have used Cerebro.
- info@cerebrocapital.com
-
12 W Madison St.
Baltimore, MD 21201 - Cerebro Capital
- @cerebrocapital